The Mortgage Rate You See Online Probably Isn’t the One You’ll Get
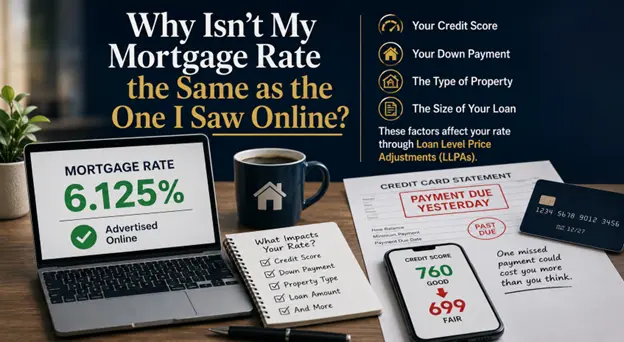
One of the most common questions I hear is:
“I saw a lower rate online. Why is my rate different?”
The short answer is that mortgage rates are personalized.
The rate you qualify for depends on several factors, including:
• Your credit score
• Your down payment
• The type of property you’re buying
• Whether it’s your primary home or an investment property
• The size of your loan
These factors affect something called a Loan Level Price Adjustment (LLPA).
What Is an LLPA?
Don’t worry about the fancy name.
Think of LLPAs as a pricing system used by Fannie Mae and Freddie Mac to measure risk.
Borrowers with stronger credit and larger down payments generally receive better pricing than borrowers with lower credit scores or smaller down payments.
That’s why two people buying similar homes may qualify for different interest rates.
One Missed Payment Could Cost You More Than a Late Fee
Many people don’t realize a single missed credit card payment can affect much more than just your credit card account.
If a payment is reported late, your credit score could drop significantly.
Why does that matter?
Because your credit score is one of the biggest factors used to determine your mortgage pricing.
A lower score may mean:
• A higher interest rate
• A higher monthly payment
• More interest paid over the life of the loan
A Real-Life Example
Recently, I worked with a young couple purchasing their first home.
The wife had an excellent credit score of 781, while the husband’s score was 719. They were planning to put 10% down.
Most conventional mortgage loans use the lower of the borrowers’ credit scores when determining pricing, so in this case the loan was priced using the husband’s 719 score.
That one difference increased the interest rate by approximately 0.50%.
In other words, they would have qualified for a rate of about 6.5% instead of 6.0%.
Rather than simply accepting the higher rate, we reviewed all of their options together. Since the wife’s income alone was sufficient to qualify, we explored whether it made sense to remove the husband from the loan application.
By doing so, we were able to use the wife’s higher credit score and secure the lower interest rate.
The lesson isn’t that one spouse should always be left off the loan. Every situation is different.
The lesson is that small differences in credit scores can have a surprisingly large impact on mortgage pricing, and sometimes there are creative solutions that can save buyers money.
And mortgages aren’t the only thing affected.
Your credit score can also impact auto insurance rates, homeowners’ insurance rates, future loan approvals, and credit card offers.
Here’s the Good News
Many of the things that affect your mortgage rate are within your control.
A few simple habits can make a big difference:
✓ Pay all bills on time
✓ Keep credit card balances low
✓ Avoid opening unnecessary new credit accounts
✓ Check your credit report regularly
One More Common Myth
Another misconception I occasionally hear is that lenders simply choose whatever rate they want to charge.
That’s not how mortgage lending works.
Mortgage loan originators are prohibited from being compensated based on the interest rate charged to a borrower.
In other words, I don’t earn more money by quoting a higher rate.
In fact, my goal is exactly the opposite.
I want to help my clients position themselves to receive the best financing available based on their individual circumstances.
The Bottom Line
The mortgage rate you see advertised online is usually based on an ideal borrower with excellent credit and a strong financial profile.
Your actual rate is based on your unique situation.
That’s why it’s so important to look beyond the headline rate and understand how your credit, down payment, and overall financial picture affect your options.
If you’re thinking about buying a home in the next year, let’s talk early. Sometimes a few small changes today can lead to better mortgage options tomorrow.